Estate Tax Exemption 2027: $15.48 Million per Person, IRS Says
The 2027 estate tax exemption is $15.48 million per person, up from $15 million, per the IRS. Year-by-year table since 2017, due dates and a printable.

Published 5 min read
Key date
- Jan 1Fri 2027 estate exclusion of $15.48 million takes effect (deaths during 2027) In 51 days + Google
In this article
- What is the estate tax exemption for 2027?
- Estate tax exclusion by year, 2017 to 2027
- How much can a married couple exclude in 2027?
- When is Form 706 due after a death in 2027?
- When must an estate file Form 706?
- What is the top estate tax rate?
- Which other 2027 estate figures did the IRS set?
- Print the 2027 estate tax fact sheet
The federal estate tax exemption for 2027 is $15,480,000 per person, the Internal Revenue Service (IRS) said on Nov. 5, 2026 in news release IR-2026-133. The release says “Estates of decedents who die during 2027 have a basic exclusion amount of $15,480,000,” “up from a total of $15,000,000 for estates of decedents who died in 2026.” Revenue Procedure 2026-35, section 3.44, repeats the figure. Below: the exclusion for every year since 2017 with our computed change, the married couple total, a Form 706 due-date table and the other 2027 estate figures, plus a free printable fact sheet.
What is the estate tax exemption for 2027?
$15,480,000 per decedent, for deaths during calendar year 2027. The IRS calls it the basic exclusion amount. It is $480,000 more than the 2026 amount of $15,000,000, a rise of 3.2% by our arithmetic.
The 2026 amount came from the Working Families Tax Cuts law, signed on July 4, 2025 as Public Law 119-21. The IRS “What’s new” page says the law “amends § 2010(c)(3) by increasing the basic exclusion amount to $15,000,000 for calendar year 2026.” Rev. Proc. 2026-35 calls the same law “commonly known as the One, Big, Beautiful Bill Act.”
Estate tax exclusion by year, 2017 to 2027
The IRS estate tax page lists a “filing threshold for year of death” for each year; it equals the basic exclusion amount. It has no 2027 row yet, so the 2027 line comes from IR-2026-133. The two change columns are our arithmetic from the IRS figures.
| Year of death | Exclusion | Change from prior year | Change, % |
|---|---|---|---|
| 2017 | $5,490,000 | n/a | n/a |
| 2018 | $11,180,000 | +$5,690,000 | +103.6% |
| 2019 | $11,400,000 | +$220,000 | +2.0% |
| 2020 | $11,580,000 | +$180,000 | +1.6% |
| 2021 | $11,700,000 | +$120,000 | +1.0% |
| 2022 | $12,060,000 | +$360,000 | +3.1% |
| 2023 | $12,920,000 | +$860,000 | +7.1% |
| 2024 | $13,610,000 | +$690,000 | +5.3% |
| 2025 | $13,990,000 | +$380,000 | +2.8% |
| 2026 | $15,000,000 | +$1,010,000 | +7.2% |
| 2027 | $15,480,000 | +$480,000 | +3.2% |
The IRS figure rises in every year of the table. The 2018 step of $5,690,000 is the largest, and the $1,010,000 step for 2026 is the largest after it. The IRS table gives no reason for the individual steps; for 2026 the IRS “What’s new” page names the Working Families Tax Cuts law. For the 2027 gift limit, see our gift tax exclusion story, and for the income tax numbers our 2027 tax brackets and limits story.
How much can a married couple exclude in 2027?
Two times $15,480,000 is $30,960,000. The IRS does not print that total, so it is our arithmetic, and it holds only when the second spouse’s exclusion is available.
The Form 706 instructions explain how. “The amount received by the surviving spouse is called the deceased spousal unused exclusion (DSUE) amount,” and “The timely filing of a complete Form 706 with DSUE will be deemed a portability election if there is a surviving spouse.” Each spouse can also use their own exclusion. The table summarizes the IRS wording.
| Question | IRS answer (Form 706 instructions, 07/2026) |
|---|---|
| What moves to the surviving spouse? | The deceased spousal unused exclusion (DSUE) amount |
| How is it elected? | A timely, complete Form 706 is “deemed a portability election” |
| Who must file for it? | The executor “elects to transfer” the DSUE amount, “regardless of the size of the decedent’s gross estate” |
Rev. Proc. 2022-32 added a later route: executors “may now file Form 706 on or before the fifth anniversary of the decedent’s death,” but only for estates that had no filing requirement under section 6018(a).
When is Form 706 due after a death in 2027?
The Form 706 instructions say “You must file Form 706 to report estate and/or generation-skipping transfer (GST) tax within 9 months after the date of the decedent’s death.” They add that “The estate and GST taxes are due within 9 months of the date of the decedent’s death.” Form 4768 gives “an automatic 6-month extension of time to file.” The instructions for 2027 deaths are not out yet, so these dates apply the 07/2026 rule to three sample dates of death. Both date columns are our arithmetic.
| Date of death | Form 706 due (9 months) | Extended filing date (+6 months) |
|---|---|---|
| Jan. 15, 2027 | Oct. 15, 2027 | April 15, 2028 |
| June 30, 2027 | March 30, 2028 | Sept. 30, 2028 |
| Dec. 31, 2027 | Sept. 30, 2028 | March 30, 2029 |
The instructions quoted here do not say what happens when a due date lands on a weekend or holiday, so the table does not apply such a rule. Put the actual date of death in the 2027 yearly calendar or the January 2027 calendar to count nine months.
When must an estate file Form 706?
The Form 706 instructions for 2026 deaths say to file for a decedent “Whose gross estate, plus adjusted taxable gifts and specific exemption, is more than $15,000,000; or” “Whose executor elects to transfer the deceased spousal unused exclusion (DSUE) amount to the surviving spouse, regardless of the size of the decedent’s gross estate.” The 2027 filing threshold is not on the IRS table yet; the release gives $15,480,000 as the 2027 exclusion.
What is the top estate tax rate?
The top rate in the IRS’s unified rate schedule is 40%. Table A of the Form 706 instructions lists it for amounts over $1,000,000, with a base of $345,800. The IRS has not published a separate 2027 rate.
Which other 2027 estate figures did the IRS set?
Rev. Proc. 2026-35 sets other estate numbers for 2027 deaths. The 2026 values come from the Form 706 instructions, “What’s New.”
| Figure | 2026 | 2027 | Rev. Proc. 2026-35 |
|---|---|---|---|
| Basic exclusion amount | $15,000,000 | $15,480,000 | section 3.44 |
| Special-use valuation (section 2032A) decrease, ceiling | $1,460,000 | $1,500,000 | section 3.45 |
| Section 6166 “2-percent portion” amount | $1,940,000 | $2,010,000 | section 3.56 |
For 2027, the special-use valuation decrease “cannot exceed $1,500,000.” Gifts to a spouse who is not a U.S. citizen are not counted as taxable gifts for the first $201,000 in 2027 (section 3.46(2)). The annual gift exclusion is $20,000, up from $19,000 (section 3.46(1)).
Print the 2027 estate tax fact sheet
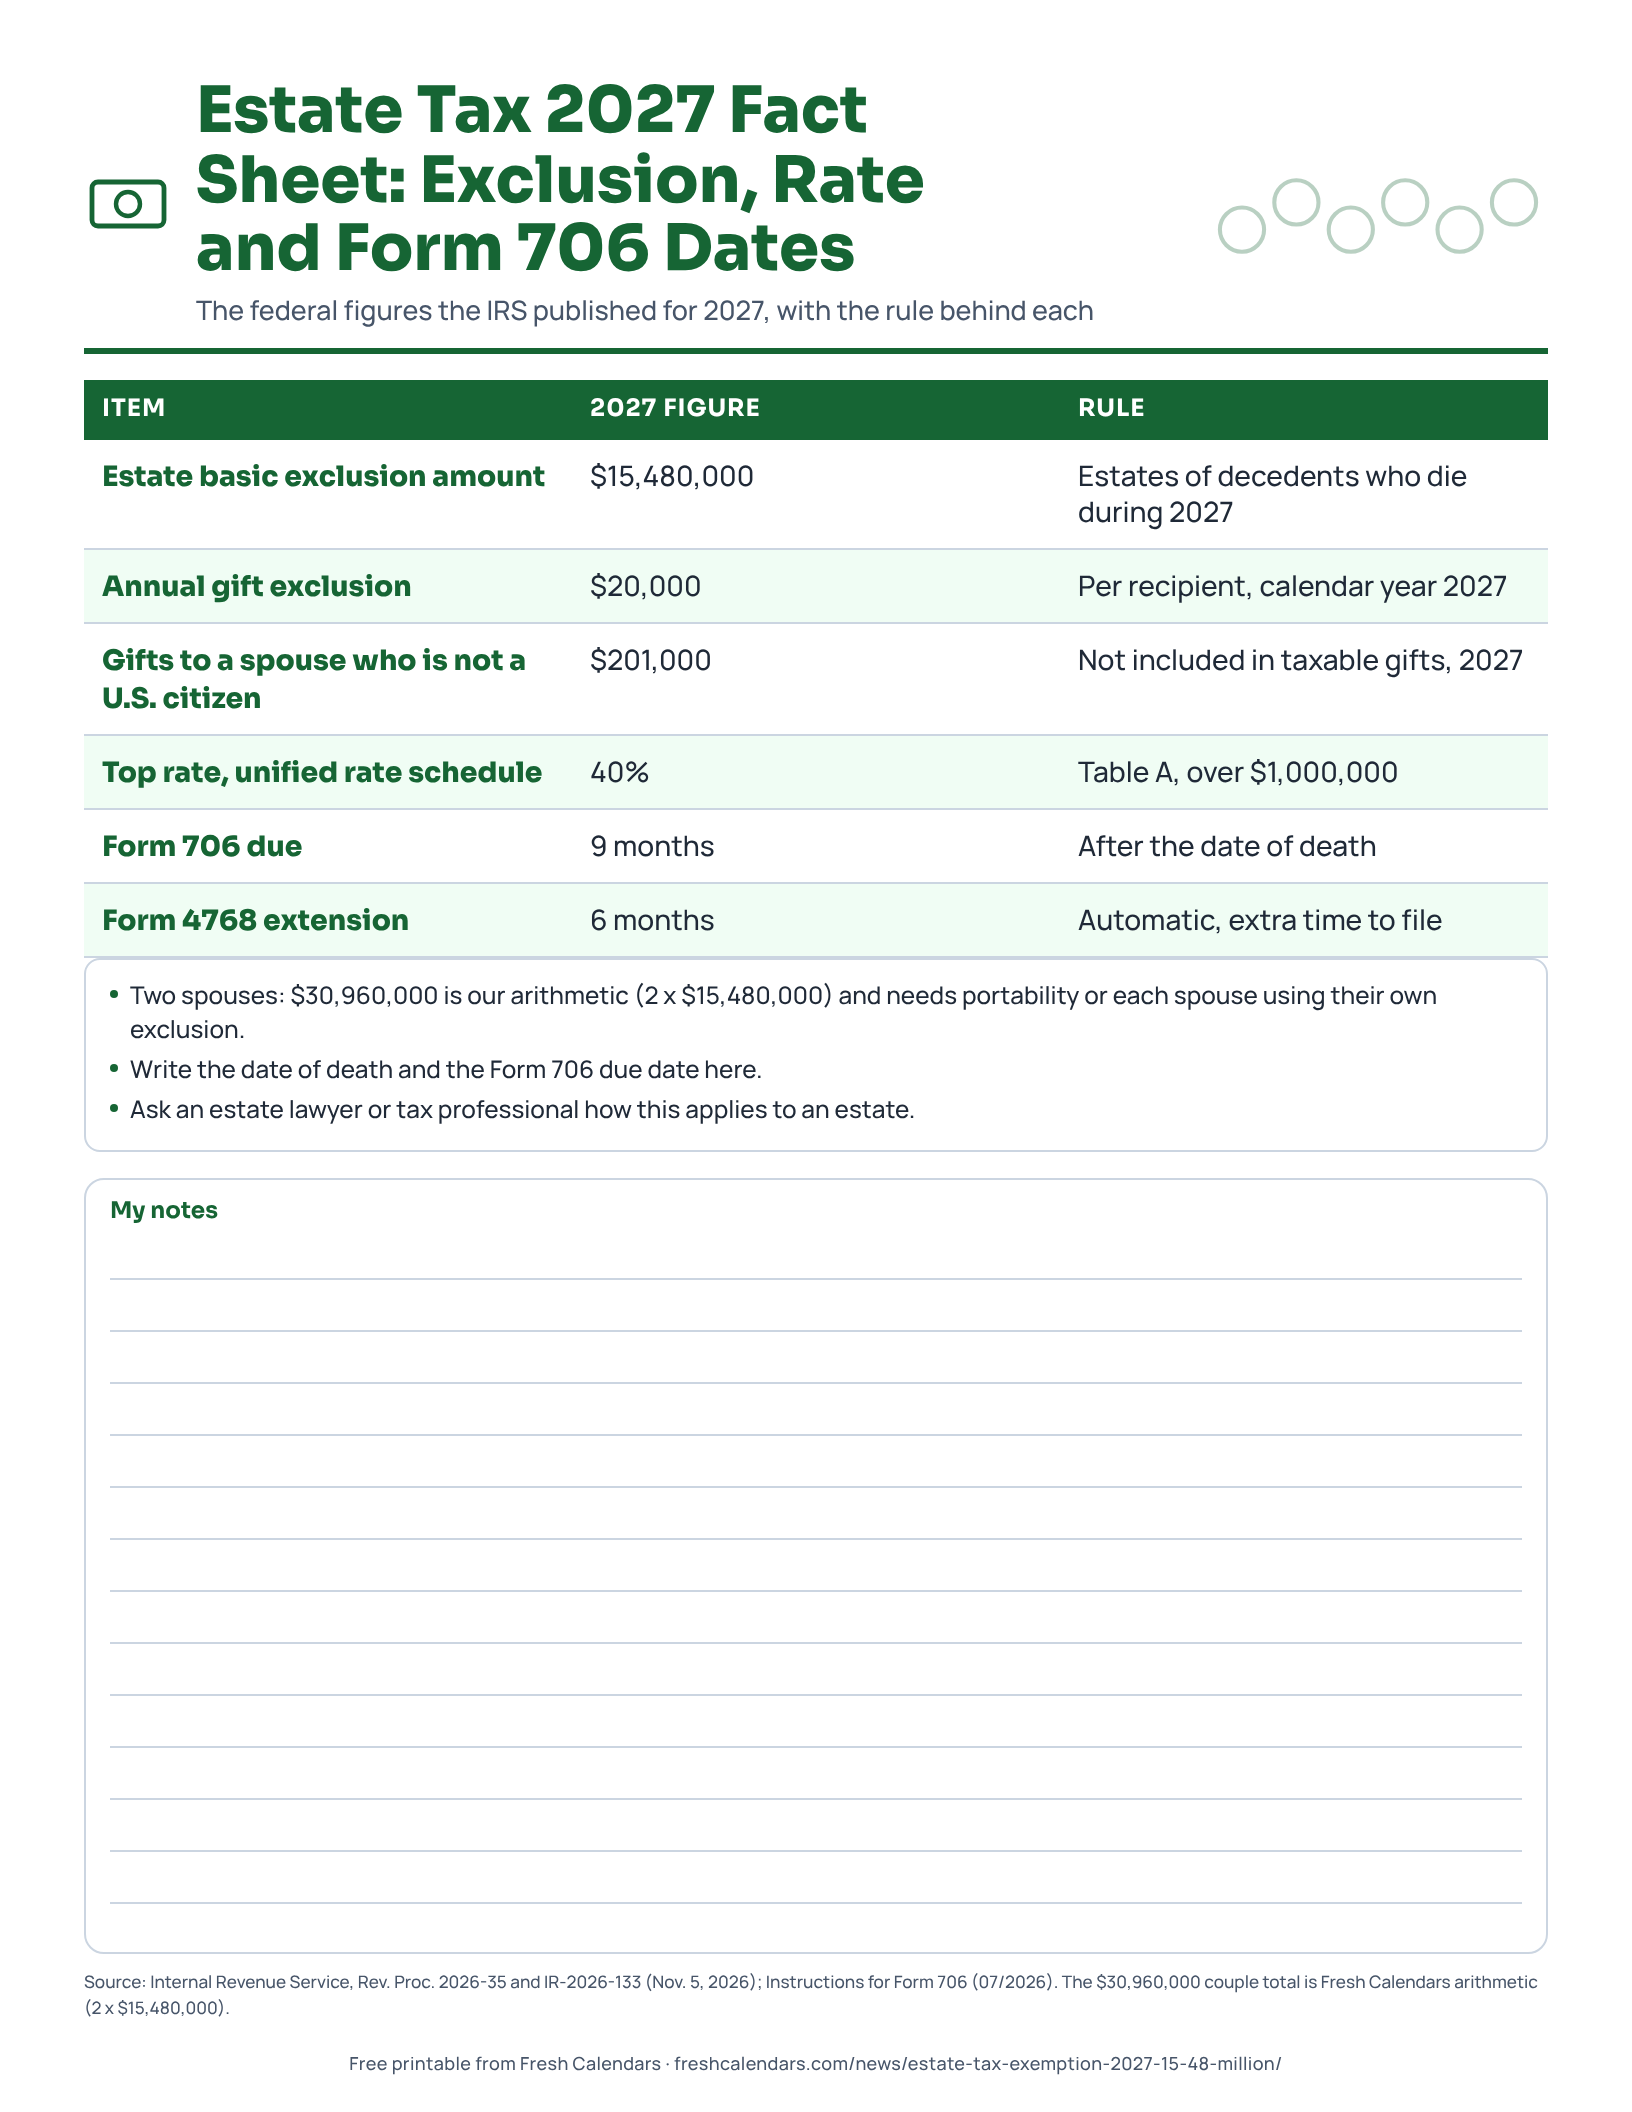
The one-page printable lists the $15,480,000 exclusion, the $20,000 gift exclusion, the $201,000 spouse figure, the 40% top rate and the Form 706 and Form 4768 time limits, each with its IRS source, plus space for a date of death and due date. Ask an estate lawyer or tax professional how these rules apply to a specific estate. Related dates sit in our 2027 tax calendar of IRS deadlines.
Free printable downloads
Every template is free, needs no sign-up and prints on US Letter paper. Choose PDF for printing or PNG for screens and documents.
Estate Tax 2027 Fact Sheet printables
-
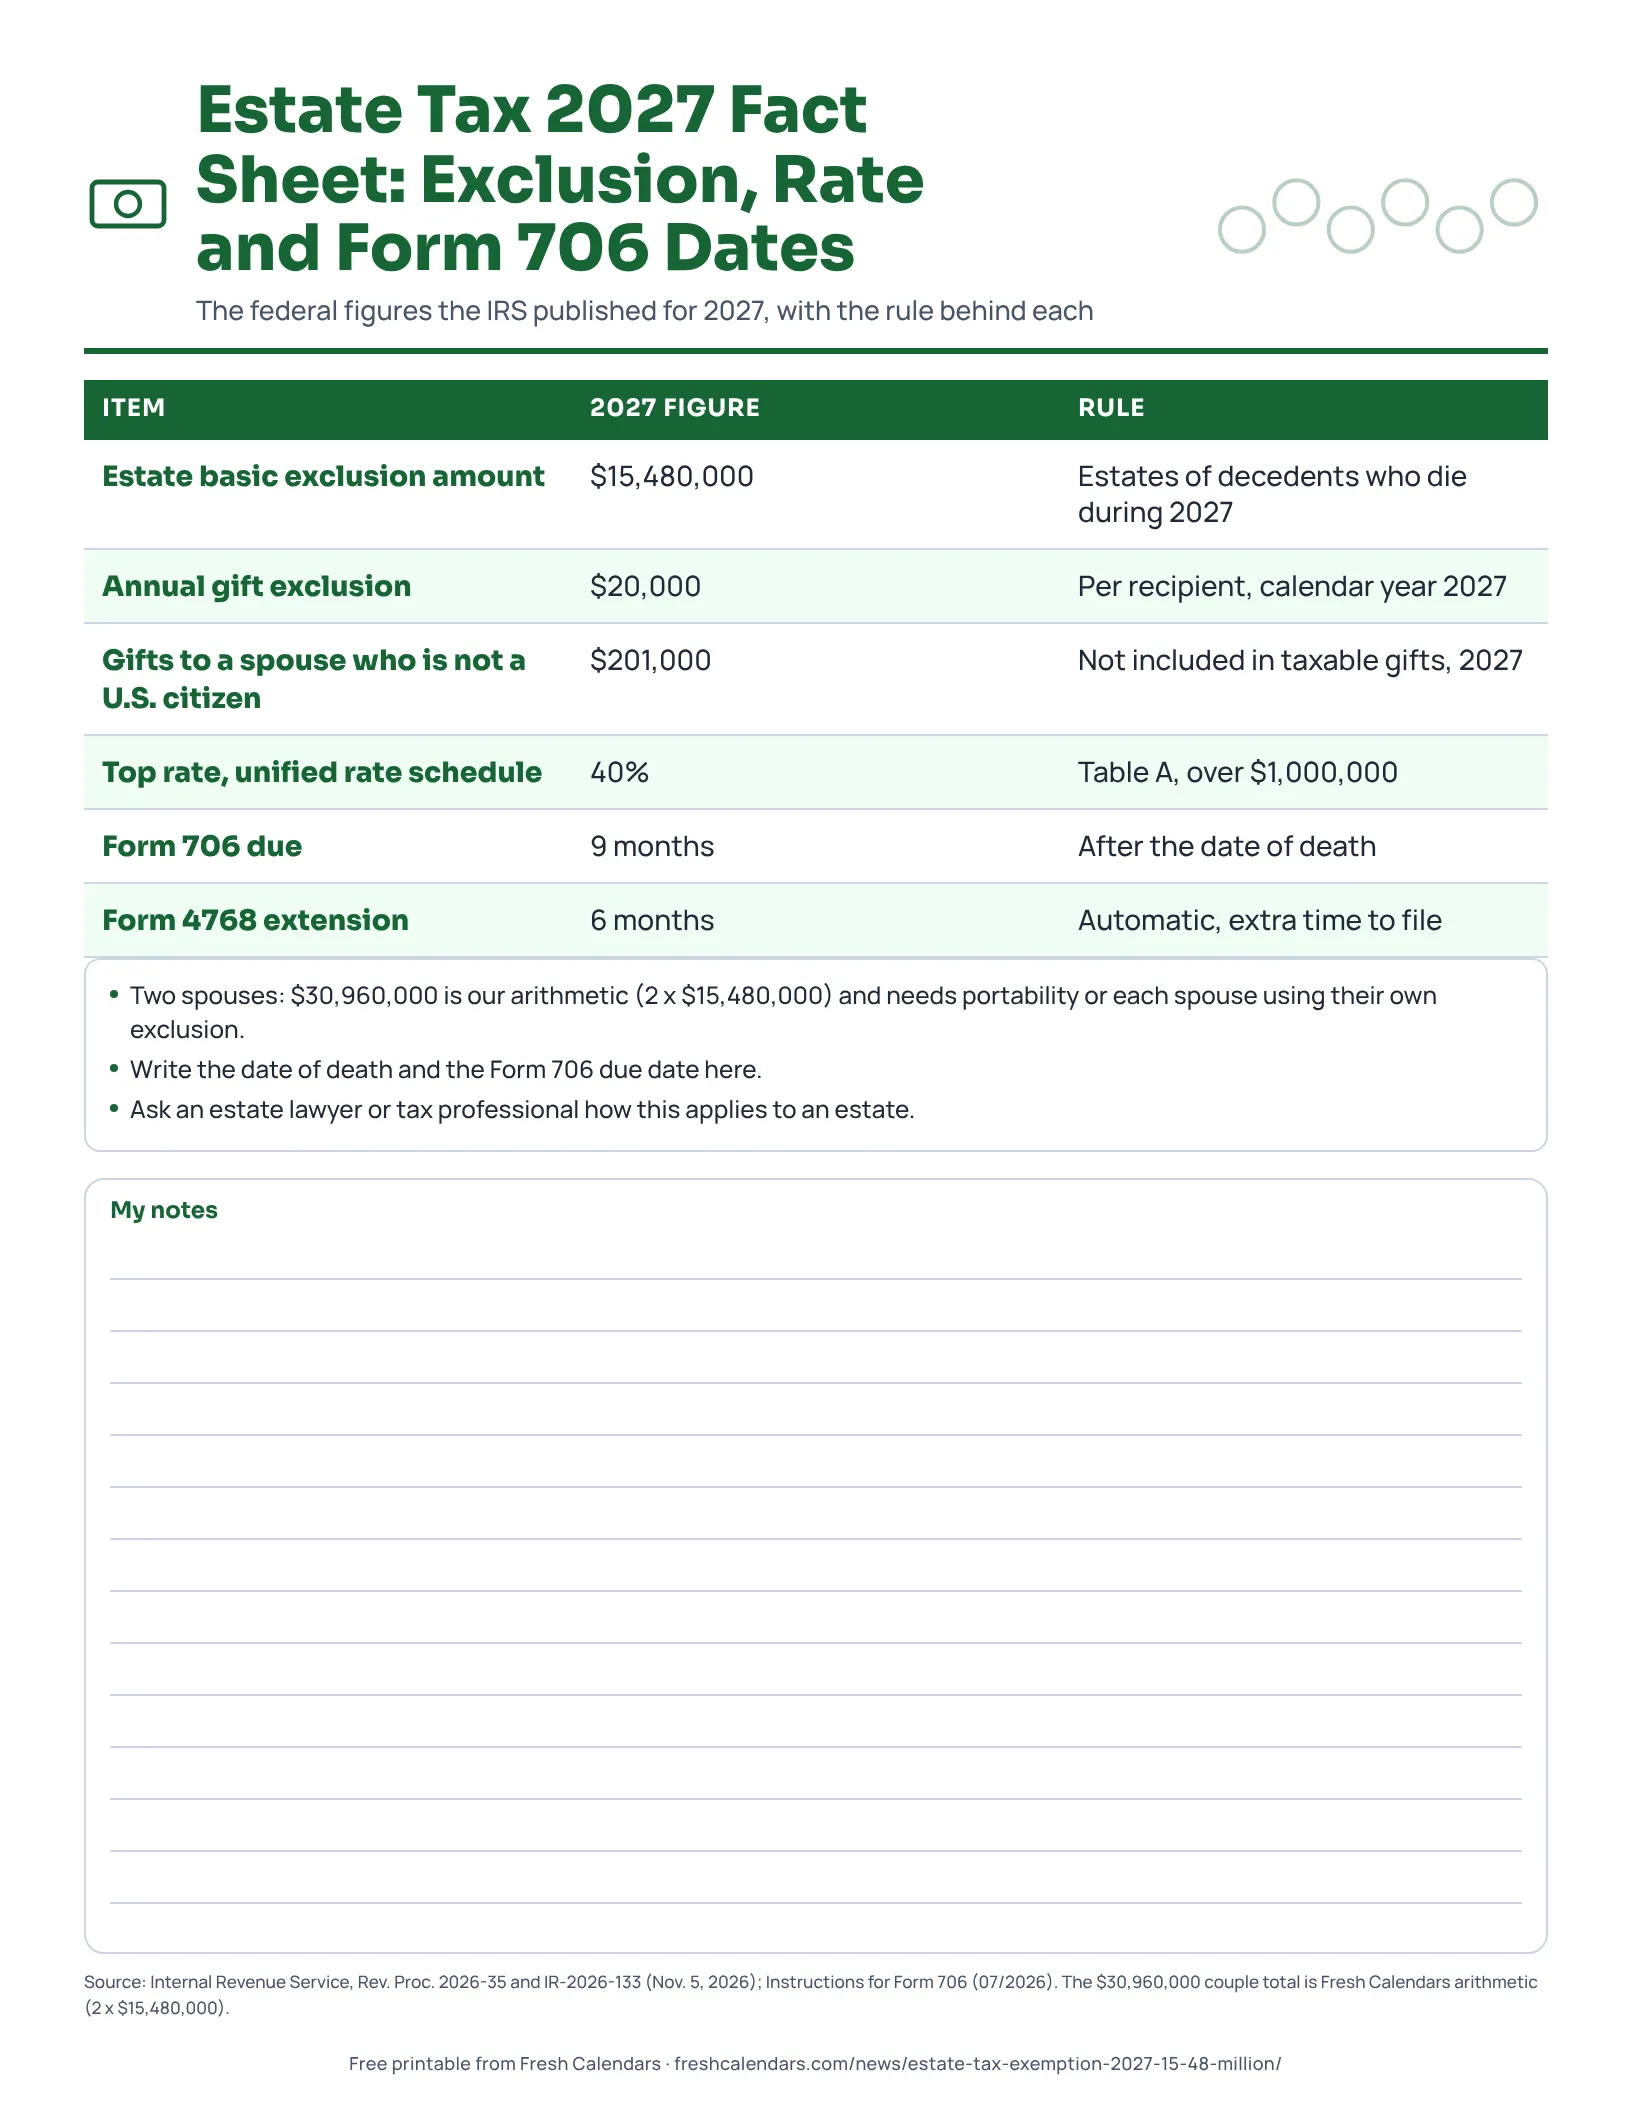
Estate Tax 2027 Fact Sheet: Exclusion, Rate and Form 706 Dates
One-page 2027 federal estate tax fact sheet: the $15,480,000 exclusion, the $20,000 gift exclusion, the 40% top rate and the Form 706 filing rules.
Frequently asked questions
Is the $15,480,000 a tax rate or a threshold?
A threshold in dollars, which the IRS calls the basic exclusion amount. The rate is separate: the top rate in the IRS's unified rate schedule is 40%.
Does the 2027 amount apply to people who die in 2026?
No. The IRS sets $15,000,000 for estates of decedents who died in 2026 and $15,480,000 for those who die during 2027.
Are state estate or inheritance taxes included?
No. The figures here are the federal amounts the IRS published. State rules are not covered on this page.
Are the 2027 Form 706 instructions out?
Not yet. The IRS estate tax page has no 2027 row in its filing threshold table, and the Form 706 instructions used here are the 07/2026 edition.
Sources
- IRS releases tax inflation adjustments for tax year 2027; taxpayers continue to benefit from the Working Families Tax Cuts (IR-2026-133) (Internal Revenue Service, 2026-11-05)
- Rev. Proc. 2026-35 (tax year 2027 inflation adjustments) (Internal Revenue Service, 2026-11-05)
- What's new - Estate and gift tax (Internal Revenue Service, 2026-11-03)
- Estate tax (Internal Revenue Service)
- Instructions for Form 706 (07/2026) (Internal Revenue Service)
- Instructions for Form 706 (PDF) (Internal Revenue Service)
- Frequently asked questions on estate taxes (Internal Revenue Service)
Related news
More in Money & Benefits
All Money & Benefits stories →- Federal Use-or-Lose Leave 2026: Schedule It by Saturday, Nov. 28
- 52-Week Money Challenge 2027: Free Printable, $1,378 by Dec. 27
- Tricare Open Season 2026: Nov. 9 to Dec. 8, Changes Start Jan. 1
- SALT Deduction Cap 2026: $40,400, Phase-Out Above $505,000
- Senior Deduction 2026: $6,000 at Age 65, Phase-Out Table
Trending now
- Veterans Day Free Meals 2026: 101 Chains and a Printable List
- Closed for Veterans Day 2026: Post Offices Shut, Stocks Trade
- King Tides Schedule 2026: California Nov. 24-26, Dec. 23-25
- National Nurse Practitioner Week 2026: Nov. 8-14, Today Show Nov. 10
- Black Friday Ads 2026: Date Is Nov. 27, Walmart Deals Nov. 23-29